

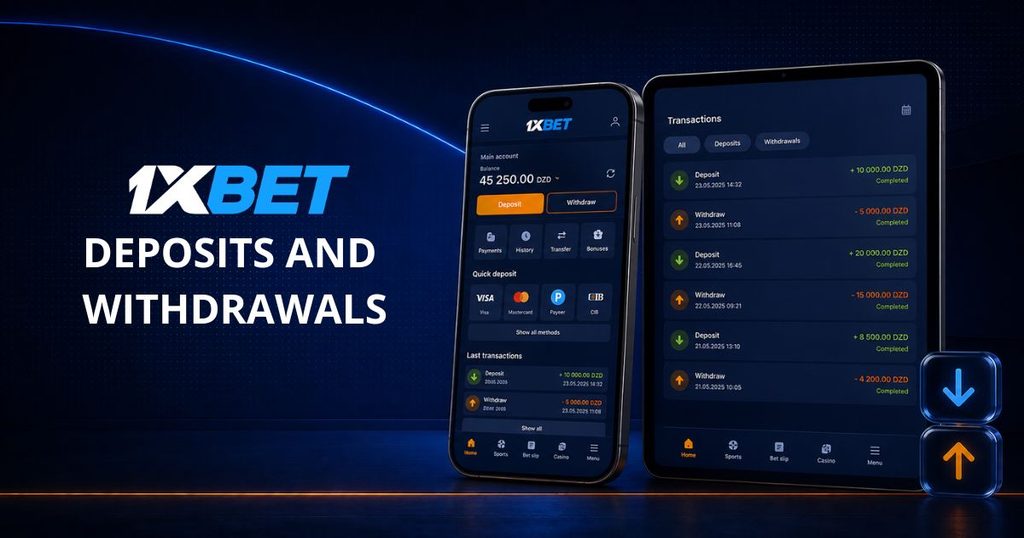
Moving money through the platform involves balance funding, payout requests, banking selection, limits, and verification checks for customers in Algeria. The cashier presents options linked to the registered currency, device, and financial history.
A 1xbet deposit may use a bank card, electronic wallet, or mobile service when that channel appears in the menu. Winnings usually return through the route previously used for funding. Minimums, maximums, charges, and processing periods differ between providers. Algerian account holders can compare available channels, submit requests in DZD, and trace the cause of a delayed or rejected operation.
1xBet Payment Methods
For Algerian customers, the banking menu controls how funds enter or leave the betting balance. More than 250 payment systems form part of the wider platform infrastructure, although a 1 xbet account displays only the channels supported for its region, currency, and profile.
| Method category | Common purpose | Main condition |
| Bank card | Deposit and eligible withdrawal | Cardholder and account names should match |
| Electronic wallet | Fast balance transfer | The wallet must belong to the registered customer |
| Mobile payment | Funding through a supported operator | Availability depends on the number and account region |
| Alternative local channel | Deposit or payout where displayed | Limits appear before confirmation |
The visible menu determines current access more accurately than a general banking list. A channel missing from this section should not be opened through an external link. DZD support, expected timing, verification status, and provider charges appear on the relevant screen before approval.
How to Fund Your 1xBet Account
A betting balance can be topped up after the customer enters the cashier from a registered profile. Each available route carries its own currency, minimum, maximum, and possible charge. The figures can differ because a bank, wallet operator, or mobile service applies separate conditions to transfers made in Algeria. The value shown beside the selected option takes priority over a general platform limit.
Ownership details need to match before money is sent. A card or wallet registered under another name can cause a failed authorization and may lead to an additional identity check during payout. The chosen profile also needs a DZD balance. Sufficient funds must cover the entered sum together with any provider charge displayed before confirmation.
- The customer signs in and opens the cashier’s deposit section.
- A listed card, wallet, mobile option, or alternative local channel is selected.
- The required sum is entered in DZD within the visible range.
- Banking details are added without changing the registered holder’s name.
- The currency, charge, final amount, and stated crediting period are reviewed.
- Bank or wallet authorization is completed when a confirmation screen appears.
- The balance and operation status are checked before another request is submitted.
One attempt needs time to finish before the same sum is sent again. Duplicate submissions can create two authorizations or leave one entry pending after the other has succeeded. A receipt, screenshot, or reference number should be retained until the funds appear. That record gives support staff the exact time, value, and identifier needed to locate the transfer.
Electronic channels are designed to credit the balance shortly after provider approval, while a bank review can extend the wait. A pending label does not by itself confirm failure. The customer can compare the financial history with the card or wallet record to determine whether a debit occurred. When money has left the source but is not visible on the platform, support can trace it by reference number. Card passwords, wallet passwords, one-time codes, and complete security codes must remain private during this review.
Freshly added funds may face turnover or financial-control checks before they become eligible for payout. The balance is intended for betting activity, not for transfers between unrelated instruments. Consistent ownership information and one verified funding route reduce the number of checks required later. They also create a clearer record when the customer requests winnings through the original channel.
Withdrawing Funds from 1xBet
Funds become eligible for payout after balance and security conditions have been met on an Algerian profile. The platform usually returns winnings through the channel used for funding, allowing the finance team to confirm ownership and follow the money trail.
- The customer opens the payout section and chooses an eligible route.
- The requested sum is entered within the displayed DZD range.
- Identity or ownership records are supplied when verification appears.
- Recipient details are checked before final confirmation.
- The request remains in financial history until its status changes.
Internal processing can range from immediate approval to 2 working days. A bank or wallet may require more time to post the funds after release. Several simultaneous requests can prolong review. The registered name, recipient’s name, and submitted documents must correspond before another attempt is created.
Transaction Limits and Fees
Every banking channel sets a lower and upper amount for transfers made through an Algerian 1xBet profile. Charges may come from the platform or an external provider. Both figures depend on status, currency, and the route chosen in the cashier.
| Transaction factor | Value or treatment |
| Account currency | DZD for a locally configured balance |
| Deposit range | Displayed beside the selected cashier method |
| Withdrawal range | Shown before the payout request is submitted |
| Processing period | Commonly up to 2 working days for withdrawal review |
| Platform or provider fee | Presented on the confirmation screen when applicable |
A large payout can trigger identity checks or require several transfers if the provider permits division. Conversion costs may arise when the source instrument uses another currency instead of DZD. The confirmation screen shows the relevant amount before approval. Reviewing that figure prevents conditions from one channel being applied incorrectly to another.
Resolving Common Payment Issues
A failed or delayed transfer can originate in the cashier, the provider’s system, or an incomplete verification check. Financial history is the first place to inspect because it distinguishes pending entries from declined and completed ones.
- A declined deposit requires sufficient funds, correct card details, and enabled online transactions.
- A debit missing from the betting balance requires its reference number, DZD amount, and submission time.
- A rejected payout requires a check of identity status, holder-name matching, and channel eligibility.
- A delayed transfer needs comparison with the stated timeframe before another request is created.
Assistance remains available 24 hours a day through the contact section. A complete case includes the profile ID, reference number, date, value, and visible status. Passwords, one-time codes, and full card security data must not be shared. Precise records let the finance team locate the affected operation without repeating work already completed.
Conclusion
Algerian customers can manage funding and payouts by using the channels displayed for their profiles and following the DZD ranges assigned to each option. Cards, electronic wallets, mobile services, and alternative local routes may appear in the cashier. Winnings normally return to the original funding source, while identity checks confirm that both instruments have the same owner. The amount, currency, charge, and processing period need review before approval. Retained reference numbers help trace delays, and 24-hour support can examine cases that remain unresolved after the stated timeframe. This process produces a consistent financial record over time without duplicating pending requests.